
Are you watching your monthly student loan statements with a growing sense of unease? You’re not alone. The sallie mae student loan interest rate can be a significant factor in your personal finances, directly influencing your disposable income and everyday spending power. For millions of Americans, student loan debt isn’t just a line item on a budget; it’s a persistent economic undertow. (See also: Boost Your Wallet: What Learn Programming Means for Your Finances)
📋 Table of Contents
At AlkaFlow, we understand that financial literacy is your most powerful tool. As a financial journalist and someone deeply interested in how economic levers affect individual lives, I want to unpack what your Sallie Mae student loan interest rate truly means for your wallet and how it ripples through the broader economy. We’ll explore how these rates are set, their direct impact on your cash flow, and strategies to manage them in today’s dynamic financial landscape.
Understanding Your Sallie Mae Student Loan Interest Rate
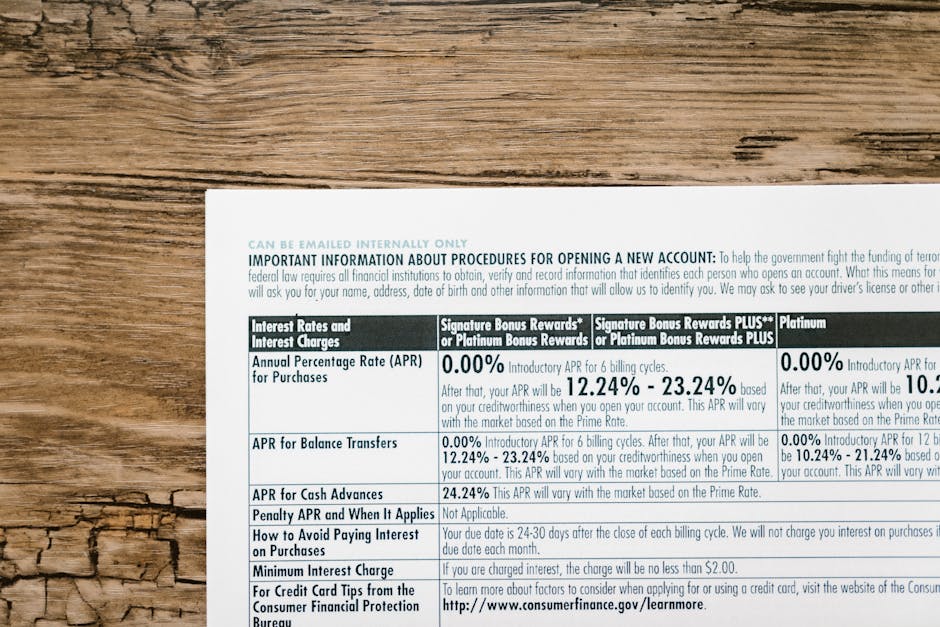
To effectively manage your student loans, you first need to understand the mechanics of the interest rate itself. Sallie Mae, as a prominent private student loan lender, offers various loan products, each with its own interest rate structure. These rates are typically either fixed or variable, and the difference can be substantial over the life of your loan.
Fixed interest rates remain constant for the entire duration of your loan. This predictability offers stability, allowing you to forecast your monthly payments with accuracy. While the initial rate might be slightly higher than an introductory variable rate, you’re shielded from future market fluctuations. On the other hand, variable interest rates are tied to an underlying benchmark, most commonly the Prime Rate or LIBOR (though LIBOR is being phased out in favor of SOFR). This means your rate can go up or down, directly impacting your monthly payment. In an environment of rising interest rates, like the one we’ve experienced recently, a variable rate can quickly lead to higher payments, squeezing your budget.
The specific rate you receive on your Sallie Mae loan is determined by several factors: your credit score, your credit history, whether you have a co-signer, and the repayment term you choose. Generally, borrowers with excellent credit scores and a strong financial history qualify for the lowest rates. It’s not uncommon for private student loan interest rates to range from 4% for highly qualified borrowers to upwards of 15% or even higher for those with less established credit or without a co-signer.
The Direct Impact of Your Sallie Mae Student Loan Interest Rate on Your Wallet
Let’s get down to brass tacks: how does this rate actually affect your day-to-day finances? A higher sallie mae student loan interest rate means more of your monthly payment goes towards interest, and less towards paying down the principal balance. This elongates the repayment period and significantly increases the total cost of your loan over time.
Consider a hypothetical loan of $30,000. If your interest rate is 6% with a 10-year repayment term, your monthly payment might be around $333. Over the life of the loan, you’d pay approximately $9,960 in interest. However, if that rate jumps to 10% (a common scenario for variable rates during economic shifts), your monthly payment could climb to nearly $396, and your total interest paid would balloon to over $17,520 – nearly double the interest for the same principal amount. This extra $63 per month might seem small, but it adds up, potentially impacting your ability to save, invest, or cover unexpected expenses.
Opportunity Cost: Loans vs. Savings
The burden of high-interest student loans also creates a significant opportunity cost. Every dollar you spend on higher interest payments is a dollar you can’t put towards building wealth. In today’s economic climate, where savings rates have become more attractive, this contrast is stark. For example, while you’re paying a high sallie mae student loan interest rate, others might be enjoying a competitive fidelity cash management account interest rate or the strong returns of a money market fund like a spaxx interest rate. Even a basic chase saving account interest rate, though often lower, still represents a positive return on your cash.
“The cost of borrowing isn’t just the interest rate; it’s also the future wealth you forgo by not investing those funds. For many, high student loan payments prevent them from entering the housing market or saving for retirement in their prime earning years.” – Economic Analyst, Grant’s Interest Rate Observer.
This perspective, often highlighted by experts like those at Grant’s Interest Rate Observer, underscores the broader economic implications. When a substantial portion of your income is allocated to debt repayment, especially high-interest debt, your ability to make discretionary purchases, save for a down payment, or invest in your future is severely curtailed. This directly affects your everyday spending, limiting everything from dining out to major purchases like a new car.
Strategies to Navigate Your Sallie Mae Student Loan Interest Rate
While the prospect of high interest rates can be daunting, you’re not powerless. Proactive management can significantly lighten your load. Here are a few strategies to consider:
1. Refinancing
If your credit score has improved since you first took out your Sallie Mae loan, or if market rates have dropped, refinancing could be a viable option. Refinancing involves taking out a new loan, often from a different lender, to pay off your existing loan. The goal is to secure a lower interest rate, a different loan term, or convert a variable rate to a fixed rate for stability. Be sure to shop around and compare offers from multiple lenders, as rates and terms can vary widely. Just remember, refinancing federal loans into private loans means losing federal protections like income-driven repayment plans. (See also: Nifty Trades Near 24,350 Level: What It Means for Your Portfolio Amid Global Shifts)
2. Accelerated Payments
Even small extra payments can make a big difference, especially if applied directly to the principal. By paying more than your minimum monthly amount, you reduce the principal balance faster, which in turn reduces the total interest you’ll pay over the life of the loan. Consider rounding up your payment, making bi-weekly payments, or applying any windfalls (bonuses, tax refunds) directly to your loan.
3. Budgeting and Debt Prioritization
Creating a detailed budget is fundamental. Understand exactly where your money is going and identify areas where you can cut back to free up funds for extra loan payments. If you have multiple debts, consider a debt snowball or debt avalanche strategy. The debt avalanche method prioritizes paying off the debt with the highest interest rate first, which is often your private student loan. This minimizes the total interest paid.
4. Understanding Your Loan Terms
Regularly review your loan statements and understand your repayment options. Sallie Mae, like other lenders, may offer deferment or forbearance options in times of financial hardship. While these can provide temporary relief, interest usually continues to accrue, potentially increasing your total loan cost. It’s crucial to weigh the short-term relief against the long-term cost.
Conclusion: Taking Control of Your Financial Future
The impact of your sallie mae student loan interest rate is undeniable, shaping not only your monthly budget but also your long-term financial trajectory. In a world where every percentage point matters, especially when juxtaposed with potential earnings from high-yield savings accounts or money market funds, understanding and actively managing your student debt is paramount. It’s about more than just paying bills; it’s about strategically navigating your financial landscape to build a more secure future.
As a crypto researcher, I often think about the power of decentralized finance and how it aims to empower individuals. While student loans are a traditional financial instrument, the principle of taking control of your financial destiny remains universal. By staying informed, being proactive with refinancing or accelerated payments, and budgeting wisely, you can mitigate the burden of student loan interest and redirect those funds towards your personal growth and wealth accumulation. Don’t let your loans dictate your financial narrative; empower yourself with knowledge and action.
Take the first step today: review your current interest rates, explore your options, and make a plan. Your financial future is in your hands.
❓ Frequently Asked Questions
What is the average Sallie Mae student loan interest rate?
Sallie Mae interest rates vary widely based on creditworthiness and loan type (fixed or variable). They can range from approximately 4% for highly qualified borrowers with fixed rates, up to 15% or more for variable rates or those with less established credit. It’s crucial to check your specific loan terms.
How does a variable Sallie Mae interest rate work?
A variable Sallie Mae interest rate is tied to a market benchmark, such as the Prime Rate or SOFR. This means your interest rate can fluctuate over time, causing your monthly payments to increase or decrease. In periods of rising interest rates, your payments will likely go up.
Can I refinance my Sallie Mae student loan?
Yes, you can often refinance a Sallie Mae student loan, especially if your credit score has improved or if current market rates are lower than your existing rate. Refinancing typically involves taking out a new loan from a different lender to pay off your Sallie Mae loan, potentially securing a lower rate or different terms.
What is the difference between a fixed and variable interest rate for student loans?
A fixed interest rate remains constant throughout the life of your loan, providing predictable monthly payments. A variable interest rate can change periodically based on market indexes, leading to fluctuating monthly payments. Fixed rates offer stability, while variable rates can be lower initially but carry more risk.
How can I lower my Sallie Mae student loan interest rate?
To potentially lower your Sallie Mae interest rate, you can consider refinancing your loan if your credit score has improved or market rates are favorable. You might also explore options like making extra payments to reduce the principal faster, or if you have a variable rate, monitoring market trends for potential drops.

0 Comments